
Digital banking is no longer a niche preference it’s how most people expect to manage money day to day. As that shift accelerates, newer names keep appearing alongside the usual roster of established banks and payment apps, and the Coyyn Com Banking App is one of them. If you’ve come across it while comparing mobile finance tools, it’s natural to want a straight answer: what does it actually offer, and is it worth trusting with your money?
This guide breaks down ten things worth knowing before you consider using the Coyyn Com Banking App, along with a closer look at its target audience, security posture, business use cases, and where the available information falls short. Rather than repeating marketing claims at face value, the goal here is to separate what’s clearly described from what still needs independent verification so you can make an informed decision either way.
Why the Coyyn Com Banking App Is Gaining Attention
Search interest around the Coyyn Com Banking App has grown steadily as more people look for mobile-first ways to manage money without visiting a physical branch. The name keeps surfacing in conversations about digital wallets, gig-economy payments, and everyday fintech tools. That visibility alone has made curious users want a clearer picture of what it actually offers.
Much of the attention comes from broader shifts in how people bank. Traditional institutions are slower to modernize, and newer platforms promise instant transfers, simplified interfaces, and fewer fees. Coyyn Com is often mentioned in that same conversation, which naturally pulls in comparison shoppers and early adopters.
Still, rising search volume isn’t the same as verified performance. A lot of the buzz comes from content sites explaining the concept rather than confirmed reviews from long-term users. That’s exactly why it’s worth breaking down what’s known, what’s unclear, and what to check before committing any money.
What Is the Coyyn Com Banking App?
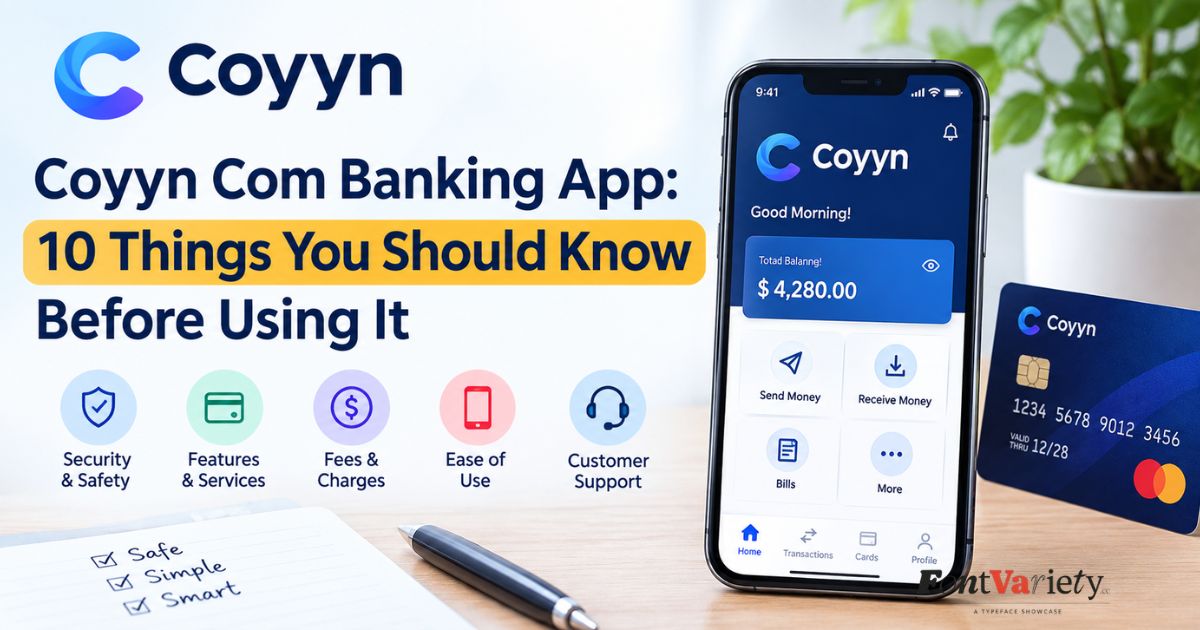
At its core, Coyyn Com is positioned as a digital finance platform that blends payment tools, account tracking, and in some descriptions, cryptocurrency features into a single mobile experience. It’s marketed toward people who want banking-style convenience without the paperwork and delays of a traditional branch visit.
It’s important to separate the marketing language from confirmed banking status. Being called a “banking app” doesn’t automatically mean a company is a chartered bank. Many fintech platforms operate by partnering with an FDIC-insured bank behind the scenes to actually hold customer deposits, and that detail matters for your money’s protection.
Before treating Coyyn Com as a full replacement for your primary bank account, it’s worth digging into its terms of service, its stated partner institutions (if any), and independent user reports. Treat it, for now, as an emerging fintech tool to evaluate carefully rather than an established bank.
1. Coyyn Com Banking App Is Built for Digital Convenience
The most consistent theme across descriptions of Coyyn Com is convenience. Everything from checking balances to sending money is designed to happen from a smartphone, cutting out the need for in-person visits or physical paperwork. That mobile-first approach mirrors where most digital banking is already headed.
For users juggling busy schedules, gig income, or multiple side projects, this kind of always-available access can genuinely simplify day-to-day money management. Not needing to plan around branch hours removes a real friction point that traditional banking still carries for a lot of people.
That said, convenience shouldn’t be the only factor in your decision. A slick, accessible app is a nice-to-have, but it doesn’t replace the need to confirm how your funds are protected and who is actually holding them behind the interface.
2. It Offers a Clean and User-Friendly Interface
User experience can make or break a financial app, and Coyyn Com is generally described as prioritizing simplicity over clutter. A clean layout matters because banking apps are used quickly and often under time pressure nobody wants to hunt through menus to send a payment.
This kind of design also lowers the barrier for people who aren’t naturally tech-savvy. A shallow learning curve means less time spent figuring out the app and more time actually using it for its intended purpose, whether that’s tracking spending or moving money between accounts.
A clean interface is a genuine usability win, but it’s worth remembering that design polish says nothing about a company’s financial backing, customer support quality, or regulatory compliance. Those are separate questions that deserve their own research.
3. Security Features Are a Key Focus
Security is consistently mentioned as a priority in how Coyyn Com is described, with references to modern protocols meant to protect user data and reduce fraud risk. In digital finance, this kind of baseline security messaging is table stakes — users won’t trust an app that doesn’t lead with it.
Common security expectations for any fintech platform include encrypted data transmission, multi-factor authentication, and monitoring for unusual account activity. If Coyyn Com offers these features, they align with what’s now considered standard practice across the industry.
Marketing language about “advanced security” is easy to write and hard to verify from the outside. Before trusting the platform with sensitive financial information, look for independent confirmation — audit disclosures, security certifications, or a clear breach-history track record — rather than taking on-site claims at face value.
4. Coyyn Com Banking App Supports Fast Transactions
Speed is one of the biggest selling points attached to Coyyn Com, with descriptions pointing to near-instant transfers instead of the multi-day waits associated with traditional bank transfers or wires. For anyone managing time-sensitive payments, that responsiveness is a meaningful upgrade.
Fast transactions matter most for freelancers, gig workers, and small businesses that depend on quick access to incoming funds. Waiting days for a payment to clear can create real cash-flow problems, so a platform built around speed directly addresses a common pain point.
Transaction speed claims should still be tested in practice. Processing times can vary depending on the payment method, the receiving bank, and whether funds move between two Coyyn Com users or out to an external account, so it’s worth confirming realistic timelines rather than assuming instant means instant in every case.
5. It Helps Users Track Spending Habits
Beyond moving money, Coyyn Com is described as offering tools to help users understand where their money goes. Spending categorization, balance tracking, and simple financial insights are increasingly standard features across modern banking apps, and Coyyn Com appears to follow that pattern.
This kind of visibility can be genuinely useful for budgeting. Seeing spending broken down by category, rather than scrolling through a raw transaction list, makes it easier to spot habits worth adjusting, whether that’s dining out too often or recurring subscriptions that have gone unnoticed.
The value of these tools depends heavily on execution how accurate the categorization is, how customizable the budgeting features are, and whether the data updates in real time. Those details are worth testing directly rather than assuming based on the feature list alone.
6. Coyyn Com Banking App Aligns with Fintech Trends
Coyyn Com fits squarely into broader fintech trends: mobile-first design, digital wallets, and growing interest in cryptocurrency alongside traditional currency management. Platforms that combine several of these elements into one app are becoming more common as user expectations shift.
This alignment with industry direction is a reasonable signal that the platform is at least keeping pace with where digital finance is heading. Bundling payments, tracking, and crypto-adjacent features under one roof reflects what a lot of newer fintech products are attempting to do.
Following a trend isn’t the same as executing it well. Plenty of apps chase the same feature checklist without matching the reliability, support, or regulatory footing of more established competitors, so trend alignment should be one data point among several, not the deciding factor.
7. It Offers Flexibility for Everyday Use
Flexibility shows up in how Coyyn Com is positioned for different use cases from everyday personal spending to managing irregular gig-economy income. An app that adapts to varied financial situations tends to have broader appeal than one built for a single, narrow use case.
This matters for people whose income or spending patterns don’t fit a traditional nine-to-five mold. Freelancers with multiple income streams, for example, benefit from tools that can handle irregular deposits and variable monthly budgets without extra manual work.
Flexibility is a genuine strength when it’s real, but it’s worth confirming which features are actually available versus which are described in general terms. Checking the current app store listing and update history can help separate active functionality from aspirational marketing copy.
8. Coyyn Com Banking App Encourages Financial Control
A recurring theme in how Coyyn Com is discussed is empowerment giving users direct visibility and control over their money rather than relying on a traditional bank’s periodic statements. Real-time balance checks and instant notifications support that sense of control.
This kind of immediate feedback loop can genuinely change financial behavior. When people see the impact of a purchase right away instead of at the end of a billing cycle, it becomes easier to course-correct spending before it becomes a bigger problem.
Financial control tools are only as good as the accuracy behind them, though. If transaction data lags or categorization is inconsistent, the sense of control the app promises can quietly become misleading, so it’s worth stress-testing this feature over a few weeks of real use.
9. It Has Potential for Future Growth
As a newer entrant in the digital finance space, Coyyn Com is often framed as having room to grow rather than being a finished, mature product. That framing is common for younger fintech platforms still building out their feature set and user base.
Growth potential can be a positive signal for early adopters who like getting in before a platform scales up, but it also means the product experience may change significantly over time — new fees, new features, or shifts in partnerships aren’t unusual as fintech companies mature.
Because the platform’s long-term trajectory isn’t yet established through years of track record, it’s reasonable to treat current features as a snapshot rather than a permanent state. Checking back periodically for updates to terms, security practices, and available services is a sensible habit here.
10. Coyyn Com Banking App Is Designed for Modern Users
Taken together, Coyyn Com is clearly built with a specific user in mind: someone comfortable managing money entirely through a smartphone, who values speed and simplicity over branch-based banking relationships. That target user increasingly represents a large share of the population.
Modern users tend to expect real-time updates, minimal friction, and self-service tools rather than needing to call a support line for routine tasks. Coyyn Com’s feature set, as described, leans into that expectation rather than trying to replicate a traditional branch experience digitally.
Whether it fully delivers on that promise is something only extended, real-world use can confirm. The design philosophy checks the right boxes on paper the next step for any prospective user is verifying that the execution matches the pitch.
Target Audience and Use Cases
Coyyn Com appears aimed at a fairly broad slice of digital-first users: freelancers managing multiple income streams, small business owners who want lighter-weight financial tools, and everyday consumers looking for a mobile alternative to branch banking. Each group has slightly different needs the app seems designed to touch on.
Gig workers, in particular, are repeatedly mentioned as a core audience. Irregular income timing makes fast visibility into incoming payments especially valuable, and tools built around tracking multiple income sources address a gap that traditional banks often overlook.
Beyond gig work, the app is also positioned for people in rural or harder-to-reach areas who benefit from not having to travel for basic banking tasks, as well as caregivers and families who want simple, at-a-glance visibility into account activity. The common thread is convenience for people who’d rather not deal with in-person banking friction.
Secure Peer-to-Peer Payments
Peer-to-peer transfers are one of the more practical features tied to Coyyn Com, letting users send money directly to other users without routing through slower traditional channels. This kind of instant, person-to-person payment has become a baseline expectation for any modern finance app.
The appeal is straightforward: splitting a bill, paying back a friend, or sending money to family shouldn’t require multiple business days or manual bank transfer forms. Peer-to-peer tools built into a mobile wallet remove that friction almost entirely when they work as intended.
As with any P2P payment feature, the details matter more than the concept. It’s worth confirming whether transfers are truly instant or just fast, whether there are limits on transfer amounts, and what recourse exists if a payment is sent to the wrong recipient protections that vary significantly between platforms.
Also Like To Read bThis: What Is Zvodeps and How Does It Work? A Complete Guide
Data Privacy and Security
Data privacy is a natural concern for any app handling financial information, and Coyyn Com’s public materials emphasize standard protective measures like encryption and account monitoring. These are baseline expectations rather than standout differentiators at this point in fintech’s evolution.
Beyond the technical safeguards, privacy also depends on how a company handles data sharing whether user information is sold to third parties, how long data is retained, and what happens to it if the company changes ownership or shuts down. These policy details are usually buried in the terms of service rather than the marketing pages.
Given that Coyyn Com’s regulatory status isn’t fully clear, it’s worth reading its privacy policy directly rather than assuming it matches the standards required of chartered banks. Financial technology companies aren’t always held to the exact same disclosure requirements as traditional banking institutions.
How Coyyn.com Benefits Businesses
For small businesses, Coyyn Com is positioned as a way to streamline day-to-day financial operations — tracking incoming payments, managing cash flow, and reducing the manual overhead that comes with juggling multiple payment methods. That kind of consolidation can save real time for lean teams.
Faster access to funds is another commonly cited business benefit. Businesses that rely on quick turnaround between receiving payment and covering expenses can be particularly sensitive to processing delays, so a platform built around speed addresses a genuine operational need.
| Business Need | How Coyyn Com Is Positioned to Help |
| Fast access to incoming payments | Near-instant transfer processing |
| Simplified cash-flow tracking | Built-in spending and balance insights |
| Reduced administrative overhead | Mobile-first, self-service account management |
| Flexible payment acceptance | Support for digital and peer-to-peer transfers |
These potential benefits are worth weighing against the same due-diligence questions that apply to individual users — confirming fee structures, deposit protections, and support responsiveness before routing business revenue through the platform.
Coyyn.com Review
Reviewing Coyyn Com honestly means separating the concept from confirmed performance. On paper, it checks a lot of boxes users want: mobile convenience, spending insights, fast transfers, and a simple interface. Those are reasonable strengths if the execution matches the description.
What’s harder to verify from the outside is long-term reliability how the app performs under real transaction volume, how responsive customer support actually is when something goes wrong, and how consistently the platform has operated over time. Independent, verified user reviews on this front are still limited.
The fairest overall take is that Coyyn Com looks like a reasonably ambitious fintech product still building its track record, rather than an established institution with years of proven performance. That’s not necessarily a dealbreaker, but it does mean prospective users should proceed with normal fintech caution: start small, verify protections, and scale usage as confidence builds.
Coyyn.com Key Statistics
Reliable, independently verified statistics on Coyyn Com’s user base, transaction volume, or growth rate aren’t publicly available at this time, and it’s worth being skeptical of any article that presents precise numbers without a clear, checkable source. That’s a normal state for a newer fintech platform, not necessarily a red flag on its own.
What can be said with more confidence is directional: digital-first banking and fintech adoption broadly have grown consistently over the past several years, driven by smartphone penetration and demand for faster payment options. Coyyn Com’s positioning fits within that larger, well-documented industry trend even without company-specific figures to cite.
If specific statistics matter for your purposes for a business decision, an investment, or a comparison article — the most reliable path is checking Coyyn.com’s own disclosures directly, along with any app store data (download counts, ratings) that’s independently tracked rather than self-reported.
Coyyn.com User Demographics and Growth
Based on how the platform is marketed, its likely user base skews toward digitally comfortable individuals: freelancers, gig workers, small business owners, and younger consumers who default to mobile-first financial tools. That audience overlaps heavily with the broader fintech adoption curve seen across the industry.
Growth for platforms like this tends to follow word-of-mouth and search-driven discovery rather than traditional bank marketing channels, which lines up with the rising search interest around terms like “Coyyn com banking app” mentioned earlier in this piece. That pattern suggests organic curiosity rather than confirmed, large-scale user adoption.
Without independently audited user numbers, any specific growth percentage would be speculative. The safest way to assess demographic fit is a practical one: consider whether your own financial habits — mobile-first, comfortable with newer fintech tools match the profile the platform appears to target.
Coyyn.com Adoption Rates
Adoption rate claims for any newer fintech platform should be treated carefully, since self-reported growth figures are easy to publish and hard to verify independently. As of now, there’s no confirmed, third-party-audited data on how many active users Coyyn Com has or how quickly that number is changing.
A more useful lens is comparative: fintech and digital banking adoption overall has climbed steadily for years, and apps that offer genuine convenience advantages over traditional banks tend to see faster uptake among younger and gig-economy users specifically. Coyyn Com’s feature set is built to appeal to exactly that segment.
For anyone evaluating adoption as a trust signal, app store ratings, review volume, and social discussion (rather than statistics quoted on the platform’s own site) tend to be more reliable indicators — and it’s worth checking those directly before assuming widespread adoption based on marketing copy alone.
Coyyn.com Business Platform Performance
Performance claims around speed and reliability are central to how Coyyn Com’s business tools are described, but platform performance is difficult to assess without direct, sustained use or independently reported uptime and processing-time data. That’s true of most fintech platforms without a long public track record.
For a business considering routing real revenue through the platform, the practical approach is to pilot it with a small volume of transactions first, tracking actual processing times, fee deductions, and support responsiveness before committing larger cash flow to it. That kind of hands-on testing tells you more than any marketing page.
It’s also worth asking directly (through the platform’s support channels) about uptime history, any past service disruptions, and how disputes or failed transactions are handled — questions that a legitimate, business-ready platform should be able to answer clearly and specifically.
Coyyn.com Pricing and Cost Comparison
Publicly confirmed, itemized pricing for Coyyn Com isn’t consistently detailed across the sources discussing it, and fee structures for fintech apps can change without much notice. Rather than quoting specific numbers that may not hold up, it’s more useful to compare the general cost categories worth checking before signing up.
| Cost Category | What to Verify Before Using Coyyn Com |
| Transfer fees | Cost per peer-to-peer or external transfer |
| Currency conversion | Markup on any cross-currency transactions |
| Account maintenance | Any monthly or inactivity fees |
| Withdrawal fees | Cost to move funds out to a traditional bank |
| Crypto-related fees | Spread or fees on any digital-asset features |
Traditional banks often bundle costs into account minimums or overdraft fees, while fintech platforms tend to favor smaller, transaction-based fees. Whichever model Coyyn Com follows, the fee schedule should be checked directly on the platform before depositing funds, since third-party articles (this one included) can’t guarantee pricing stays current.
Key Features at a Glance
| Feature | What It Offers |
| Mobile-first banking | Manage accounts entirely from a smartphone |
| Clean interface | Simplified design with a low learning curve |
| Security protocols | Encryption and account monitoring |
| Fast transactions | Near-instant transfers between users |
| Spending insights | Categorized tracking of financial habits |
| Peer-to-peer payments | Direct transfers between platform users |
| Business tools | Cash-flow tracking and payment consolidation |
| Crypto-adjacent features | Digital asset management alongside traditional funds |
This snapshot reflects how Coyyn Com is publicly described rather than independently verified performance data, so it’s worth treating it as a starting checklist for your own evaluation rather than a confirmed feature guarantee.
Pros and Cons of Coyyn Com Banking App
On the positive side, Coyyn Com brings together several features users genuinely want in one place: a clean mobile interface, fast transfers, spending insights, and tools aimed at freelancers and small businesses. For someone comfortable with newer fintech products, that combination can be a real convenience upgrade over a traditional bank.
On the negative side, the platform’s regulatory status isn’t clearly confirmed as a chartered, FDIC-insured bank, and independently verified statistics on its user base, performance, and pricing are limited. That uncertainty matters more for a financial product than it would for, say, a productivity app, since real money and consumer protections are on the line.
| Pros | Cons |
| Mobile-first convenience | Regulatory/FDIC status not clearly confirmed |
| Clean, simple interface | Limited independently verified user data |
| Fast transaction speeds | Pricing details not consistently published |
| Useful spending-tracking tools | Shorter track record than established banks |
| Aligned with fintech trends | Long-term reliability still unproven |
The reasonable takeaway: Coyyn Com’s feature list is appealing, but it’s a newer platform without a fully established track record. Anyone considering it should verify its regulatory status, read the current terms directly, and start with small, low-risk transactions before relying on it for significant financial activity.
Frequently Asked Questions
Is the Coyyn Com Banking App a real bank?
Coyyn.com does not currently appear in the FDIC BankFind Suite as a chartered or federally insured bank. It’s positioned as a fintech platform, which may or may not partner with a licensed bank behind the scenes to hold deposits — that partnership isn’t clearly confirmed in public materials, so it’s worth asking directly before depositing funds.
Is my money FDIC-insured if I use Coyyn Com?
Not automatically. FDIC insurance applies to funds held at chartered, insured depository institutions. Unless Coyyn.com clearly discloses a specific FDIC-insured partner bank holding your deposits, you shouldn’t assume the same protections as a traditional bank account apply.
What features does the Coyyn Com Banking App offer?
Based on public descriptions, it includes mobile account management, peer-to-peer payments, spending tracking, fast transfers, and some crypto-adjacent tools. Feature availability should be confirmed in the current app listing, since fintech products update frequently.
Is the Coyyn Com Banking App good for freelancers and gig workers?
Its feature set fast access to incoming payments, spending insights, and flexible account management is clearly aimed at that audience. Whether it performs well in practice for irregular income streams is best tested with a small trial period before relying on it fully.
How much does Coyyn Com cost to use?
A fully itemized, verified fee schedule isn’t consistently published across available sources. Check transfer fees, withdrawal costs, currency conversion charges, and any account maintenance fees directly on the platform before signing up.
Is the Coyyn Com Banking App safe to use?
It references standard security measures like encryption and account monitoring, which align with industry norms. However, “safe” also depends on regulatory status and deposit protection, which aren’t fully confirmed so treat security features and financial protections as two separate questions.
Should I switch my primary bank account to Coyyn Com?
Given the current lack of confirmed regulatory status and limited independently verified track record, it’s more sensible to treat Coyyn Com as a supplementary tool to test cautiously rather than a full replacement for an FDIC-insured primary bank account.
Conclusion
The Coyyn Com Banking App checks a lot of boxes that modern users look for: a clean mobile interface, fast transfers, spending insights, and tools tailored to freelancers and small businesses. That combination explains why it’s picking up search interest and curiosity from people comparing digital finance options.
At the same time, several important questions remain open — its regulatory status, verified user statistics, and a fully published fee schedule chief among them. None of that means the platform is untrustworthy, but it does mean it hasn’t yet built the kind of long, transparent track record that traditional banks and more established fintech competitors have.
The most sensible path forward is a cautious one: verify Coyyn.com’s current terms and any bank partnerships directly, start with small transactions rather than your full financial life, and keep an eye on how the platform’s disclosures and reviews evolve over time. Approached that way, the Coyyn Com Banking App is worth exploring just not worth trusting blindly.